AOC-4 and MGT-7 due dates for FY 2025-26
Every company files its financial statements in AOC-4 and its annual return in MGT-7 or MGT-7A after the annual general meeting. The clock runs from the AGM, not from the year end, and each day of delay adds ₹100 per form.
Reviewed by Vijay Dhawan, Managing Partner, LexVerge LLP, on · Published
Quick answer
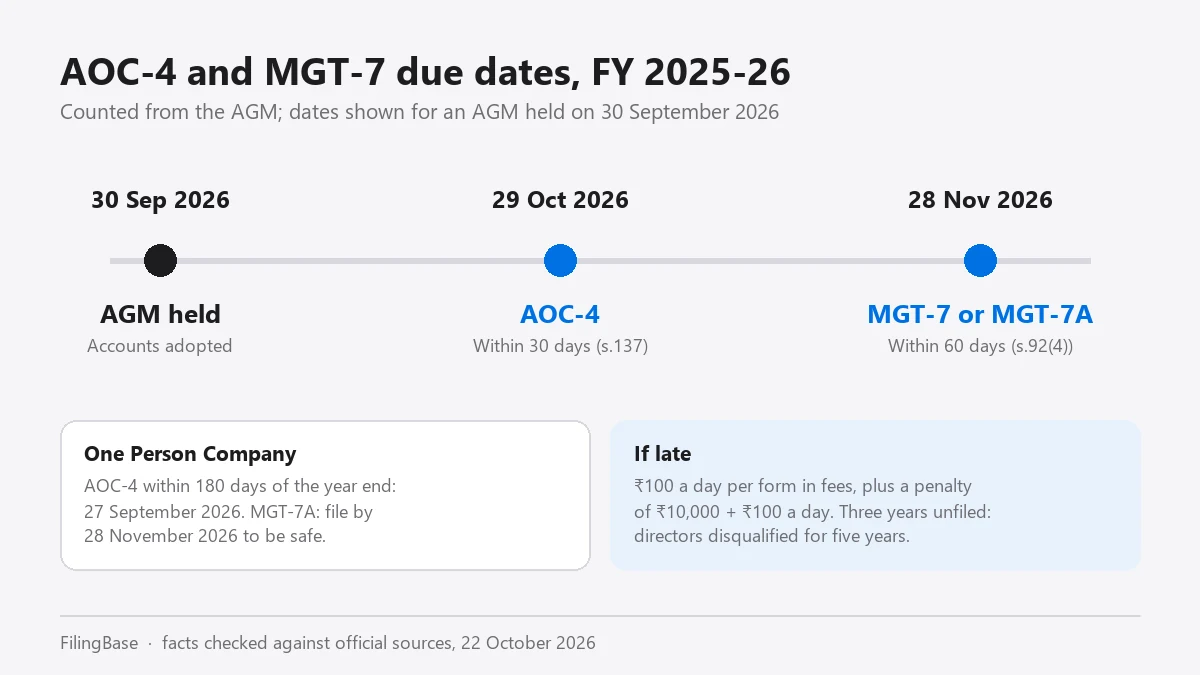
For an AGM held on 30 September 2026, the last date for FY 2025-26, file AOC-4 by 29 October 2026 and MGT-7 or MGT-7A by 28 November 2026. The Act allows 30 and 60 days from the AGM; we count the AGM day itself, which gives the safer date one day earlier. A One Person Company files AOC-4 within 180 days of the year end, which was 27 September 2026.
Want the forms filed for you? See our ROC filing service.
Already late? The free ROC late fee calculator works out the MCA fees for every overdue AOC-4, MGT-7, Form 8 and Form 11.
New to the jargon? The compliance glossary defines 45 company, GST and income-tax terms.
Need this done for you?
Need AOC-4 and MGT-7 filed before the late fee builds up?
From ₹1,999 + MCA fees
The forms and their deadlines
| Form | What it carries | Due | Section |
|---|---|---|---|
| AOC-4 | Audited balance sheet, profit and loss account, board’s report and auditor’s report. AOC-4 XBRL for companies that must file in XBRL; AOC-4 CFS for consolidated statements | 30 days from the AGM | 137(1) |
| AOC-4 by an OPC | Financial statements adopted by the member | 180 days from the end of the financial year | 137(1), third proviso |
| MGT-7 | Annual return of a company that is not a small company or an OPC | 60 days from the AGM | 92(4) |
| MGT-7A | Annual return of a small company or an OPC | 60 days from the AGM | 92(4) |
A small company is one with paid-up capital up to ₹10 crore and turnover up to ₹100 crore, the limits in force since 1 December 2025. If the AGM is held earlier than 30 September, count from the actual date: an AGM on 15 September puts AOC-4 at 14 October and MGT-7 at 13 November.
If the AGM is not held, or the accounts are not adopted
Where the financial statements are not adopted at the AGM, the unadopted statements are still filed in AOC-4 within 30 days of the AGM, and the adopted ones follow once approved. Where no AGM is held at all, the annual return is still due within 60 days of the date on which the AGM should have been held, with a statement of the reasons. An OPC holds no AGM; file its MGT-7A by 28 November 2026 to be safe.
Late fees and penalties
Each form attracts an additional fee of ₹100 for every day of delay, on top of the normal filing fee. The fee keeps running until the form is filed, and two forms filed 60 days late cost ₹12,000 in additional fees alone.
| Default | Company | Officers |
|---|---|---|
| AOC-4 not filed in time, section 137(3) | ₹10,000, plus ₹100 a day, up to ₹2 lakh | Managing director and CFO (or the responsible director, or all directors): ₹10,000, plus ₹100 a day, up to ₹50,000 |
| MGT-7 or MGT-7A not filed in time, section 92(5) | ₹10,000, plus ₹100 a day, up to ₹2 lakh | Every officer in default: ₹10,000, plus ₹100 a day, up to ₹50,000 |
The penalties are separate from the additional fee and are imposed by the Registrar through adjudication. The bigger risk is section 164(2)(a): a company that has not filed financial statements or annual returns for three continuous financial years disqualifies every director from reappointment there and from appointment elsewhere for five years.
What to have ready
- Audited financial statements signed by the board and the auditor, with the board’s report and its annexures.
- The date of the AGM and the resolution adopting the accounts.
- For MGT-7 or MGT-7A, the list of shareholders and debenture holders, and form MGT-8 from a practising company secretary where paid-up capital is ₹10 crore or more or turnover is ₹50 crore or more.
- A director’s DSC registered on the MCA portal, and the DIN with a current DIR-3 KYC.
- CSR details where section 135 applies; CSR-2 is now an addendum to AOC-4.
Our annual compliance plan covers both forms, the AGM papers and the director KYCs, and the compliance calendar lists every date in the year.
Frequently asked questions
What is the due date for AOC-4 for FY 2025-26?
Thirty days from the AGM. For an AGM on 30 September 2026 that is 29 October 2026 counting the AGM day, or 30 October counting from the next day; file by 29 October to be safe. An OPC files within 180 days of 31 March, by 27 September 2026.
What is the due date for MGT-7 and MGT-7A for FY 2025-26?
Sixty days from the AGM: 28 November 2026 for an AGM on 30 September 2026, counting the AGM day. MGT-7A is the shorter form for small companies and OPCs; the deadline is the same.
What is the late fee for AOC-4 and MGT-7?
₹100 for each day of delay, per form, in addition to the normal filing fee. Penalties under sections 137(3) and 92(5) can be imposed separately.
Who files MGT-7A instead of MGT-7?
Small companies, meaning paid-up capital up to ₹10 crore and turnover up to ₹100 crore, and One Person Companies. Other companies file MGT-7.
What happens if a company does not file AOC-4 and MGT-7 for three years?
Under section 164(2)(a) every director becomes ineligible to be reappointed in that company or appointed in any other company for five years. The Registrar may also start strike-off proceedings against a company that is not carrying on business.
Keep this on your desk.
Compliance calendar FY 2026-27 (PDF)
Every MCA, GST, income-tax, PF and ESI due date from April 2026 to March 2027 on one page, with the extended audit dates.
Compliance calendar for Google or Outlook (.ics)
The same dates as calendar reminders: import once and every deadline appears in your calendar.
Annual Compliance for a Private Limited Company from ₹4,999 a year, by a CA.
AOC-4, MGT-7A, two director KYCs, DPT-3 and AGM documents, every year, on time.
Professional fee shown; government charges at actuals, quoted in writing before you pay. GST at 18% extra.
See what is included and the full priceAGM done, forms not filed?
We prepare and file AOC-4 and MGT-7 or MGT-7A, with the board report and AGM papers, before the next day’s fee runs.
Keep reading.
DPT-3: the return of deposits and loans
Form DPT-3 is filed by 30 June each year with figures as on 31 March, for deposits and for loans and advances not treated as deposits.
Read guide→GuideForm ADT-1: filing the auditor’s appointment
ADT-1 is filed within 15 days of the meeting that appoints the auditor, once for each five-year term: who files it, the first auditor question, attachments and fees.
Read guide→GuideForm MGT-14: filing resolutions with the Registrar
Special resolutions and specified board resolutions go to the Registrar in MGT-14 within 30 days: what is covered, what private companies can skip, and the penalty.
Read guide→Official references
The statutory sources behind this page. We keep our guidance aligned to them: verify anything time-sensitive directly.
- Ministry of Corporate AffairsCompanies Act filings, forms and fee schedules
- Income Tax DepartmentReturns, forms, rates and e-filing utilities
- GST PortalRegistration, returns and rate notifications
Facts on this page are checked against these sources; the date of the last check is shown at the top of the page. It is general guidance, not advice on your specific facts. How we write and check our guides.