Tax on FD interest: how it is taxed and how to handle the TDS
Fixed deposit interest is fully taxable at your slab rate, whether or not the bank deducts TDS and whether or not you withdraw it. What changed recently is the TDS threshold, and from 1 April 2026 the forms: Forms 15G and 15H are now Form 121.
FilingBase editorial team · Facts checked against official sources on · Published
Quick answer
FD interest is taxed at your slab rate every year as it accrues, even on cumulative deposits. Banks deduct 10% TDS once interest crosses ₹50,000 a year (₹1 lakh for senior citizens). Forms 15G and 15H have been replaced by a single Form 121 under the Income-tax Rules, 2026.
- TDS thresholds: ₹50,000 / ₹1 lakh for seniors
- 20% TDS without PAN
- Seniors: ₹50,000 interest deduction in the old regime
Official source: Income Tax Department: FAQs on forms under the Income-tax Rules, 2026
How FD interest is taxed
- Taxed as income from other sources at your slab rate, in the regime you choose.
- Taxed on accrual: interest on a cumulative FD is taxable every year as it accrues, not only at maturity. Banks deduct TDS yearly on accrued interest for this reason.
- Interest on a joint FD is taxed in the hands of the first holder unless the money came from another holder.
- Interest on an FD made from a gift to a spouse or minor child is generally clubbed with the giver’s income.
The 5-year tax-saver FD gives a deduction on the principal in the old regime, but its interest is still taxable every year; see our Section 80C guide.
TDS on FD interest
| Payer | Payee | TDS threshold per year | Rate |
|---|---|---|---|
| Bank, co-operative bank, post office | Senior citizen (60+) | ₹1,00,000 | 10% |
| Bank, co-operative bank, post office | Others | ₹50,000 | 10% |
| Company or NBFC deposit | Anyone | ₹10,000 | 10% |
| Any payer | No PAN given | From the first rupee above the threshold | 20% |
| Any payer | Non-resident (NRO FD) | No threshold | 30% plus surcharge and cess, or treaty rate |
The bank thresholds were raised from ₹40,000 and ₹50,000 on 1 April 2025. They apply per bank, across all branches, not per deposit. NRE and FCNR deposits are tax-free for non-residents.
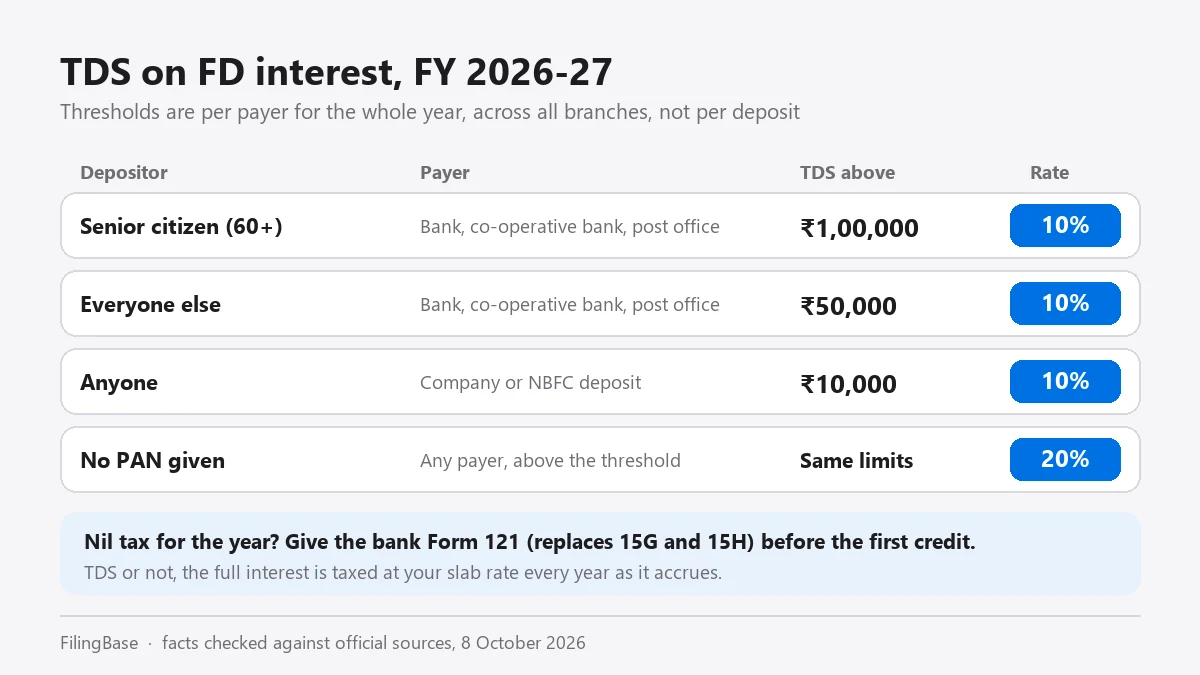
Avoiding TDS: Form 121 (formerly 15G and 15H)
- Under the Income-tax Rules, 2026, a single Form 121 replaces Form 15G (for people under 60) and Form 15H (for seniors).
- You can give it if the tax on your estimated total income for the year is nil. For people under 60, the interest itself must also be within the basic exemption limit; seniors can give it whenever their tax is nil after rebate and deductions.
- Submit it at the start of the year, to each bank, before the first interest credit.
- A false declaration is an offence. If your income will be taxable, let the TDS happen and adjust it in the return.
Relief for senior citizens
- Deduction of up to ₹50,000 on interest from banks, co-operative banks and post office deposits, including FDs (formerly section 80TTB), in the old regime only. Non-seniors get ₹10,000 on savings account interest only.
- Higher basic exemption in the old regime: ₹3 lakh at 60, ₹5 lakh at 80. The new regime has the same slabs for everyone, with income up to ₹12 lakh tax-free after the rebate; see our 87A rebate guide.
- Seniors aged 75 or more with only pension and interest from the same bank can file a declaration and let the bank deduct the full tax, with no return needed.
- Seniors with no business income are exempt from advance tax.
Reporting in the return
- Download the AIS and Form 26AS; they show interest and TDS bank by bank. See our Form 26AS and AIS guide.
- Report the full accrued interest, including on cumulative FDs, under income from other sources.
- Claim credit for the TDS.
- If your slab is above 10%, pay the difference as advance or self-assessment tax to avoid interest; see our advance tax guide.
Worked example
Meena, 45, has FDs with two banks: interest of ₹60,000 from Bank A and ₹30,000 from Bank B for FY 2026-27. Her salary is ₹14 lakh, new regime.
- Bank A deducts 10% TDS on ₹60,000 (above the ₹50,000 threshold): ₹6,000.
- Bank B deducts nothing (below the threshold).
- In her return she reports ₹90,000 of interest. Her marginal rate is 15% plus cess, so tax on the interest is about ₹14,040.
- She pays the balance of about ₹8,040 as self-assessment tax before filing, or through her employer if she declared the interest to them.
She cannot give Form 121 to Bank A, because her total income is taxable.
Frequently asked questions
Is FD interest taxable?
Yes, fully, at your slab rate as income from other sources, every year as it accrues, even on cumulative FDs.
What is the TDS limit on FD interest in 2026?
₹50,000 a year per bank for non-seniors and ₹1 lakh for senior citizens. For company deposits the limit is ₹10,000.
What replaced Form 15G and 15H?
Form 121 under the Income-tax Rules, 2026, a single declaration for both non-seniors and seniors.
Is TDS on FD the final tax?
No. TDS is 10%; if your slab rate is higher you pay the balance, and if your income is lower you claim a refund.
How much FD interest is tax-free for senior citizens?
In the old regime, a deduction of up to ₹50,000 on bank and post office interest. In the new regime, total income up to ₹12 lakh is effectively tax-free after the rebate.
TDS on interest eating into your returns?
A FilingBase CA works out the right regime and claims your refund, from ₹499.
Keep reading.
ITR Refund Status: How to Check It, What Each Status Means, Why Refunds Get Stuck, and How to Get a Failed Refund Reissued
Where to see the status, what each status means, the seven reasons refunds stall, the reissue request, and interest at 6% a year on delayed refunds.
Read guide→GuideForm 26AS and the Annual Information Statement: How to Download Them, What Each Shows, and How to Fix Entries That Are Wrong
The tax-credit statement and the everything-statement: how to download both, what the department already knows about you, and how to contest a wrong entry.
Read guide→GuideSection 80C deduction list 2026
Every item that counts toward the ₹1.5 lakh limit, the current small-savings rates, and when claiming 80C still beats the new regime.
Read guide→Official references
The statutory sources behind this page. We keep our guidance aligned to them — verify anything time-sensitive directly.
- Ministry of Corporate AffairsCompanies Act filings, forms and fee schedules
- Income Tax DepartmentReturns, forms, rates and e-filing utilities
- GST PortalRegistration, returns and rate notifications
Facts on this page are checked against these sources; the date of the last check is shown at the top of the page. It is general guidance, not advice on your specific facts. How we write and check our guides.