Advance tax due dates 2026-27: who pays, when, and what a shortfall costs
Tax is meant to be paid as income is earned, not when the return is filed. If your employer’s TDS covers everything, you can stop reading. If it does not, there are four dates a year, and missing them is priced at one percent a month.
Reviewed by Vijay Dhawan, Managing Partner, LexVerge LLP, on · Published
Quick answer
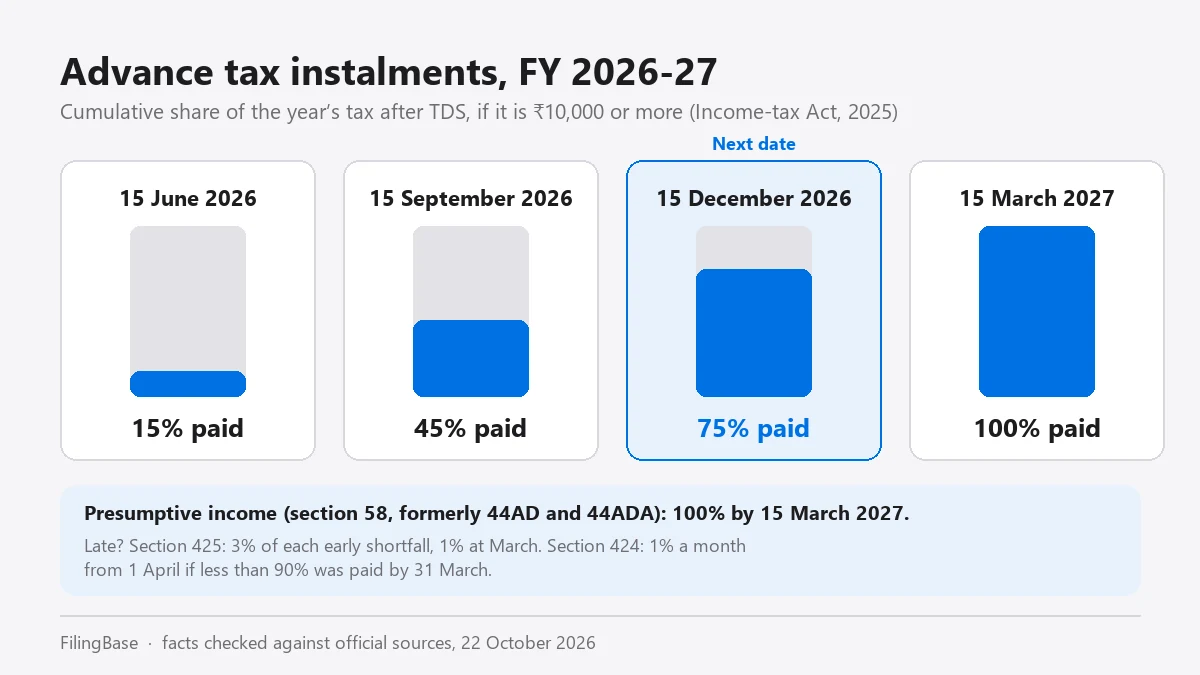
The next advance tax date is 15 December 2026, by which 75% of the year’s tax after TDS must have been paid. The dates for FY 2026-27 are 15 June (15%), 15 September (45%), 15 December (75%) and 15 March 2027 (100%); presumptive taxpayers pay everything by 15 March. Work out your instalments and any interest with our advance tax calculator.
Presumptive or books? The free presumptive tax calculator compares the tax on both routes for 2026-27.
Turnover close to the threshold? Check the tax audit limit: the ₹1 crore and ₹10 crore tests.
Need this done for you?
Business or freelance income? Our CA works out your advance tax and files the return.
ITR for business from ₹1,199
Who has to pay
Anyone whose estimated tax for the year, after subtracting tax deducted and collected at source, is ₹10,000 or more. That covers most freelancers, professionals and business owners, and a surprising number of salaried people: those with rent, interest, capital gains, a second employer, or a job change where the new employer did not count the earlier salary.
A resident senior citizen aged 60 or above with no income from business or profession is exempt, and pays any balance as self-assessment tax with the return. Non-residents with Indian income are within advance tax like anyone else.
The four instalments
| On or before | Cumulative share of the year’s tax |
|---|---|
| 15 June | 15% |
| 15 September | 45% |
| 15 December | 75% |
| 15 March | 100% |
Taxpayers on presumptive taxation under sections 44AD or 44ADA (section 58 of the Income-tax Act, 2025) pay the whole amount in a single instalment by 15 March. Any tax paid up to 31 March counts as advance tax for the year. For financial year 2026-27 the dates are 15 June, 15 September and 15 December 2026 and 15 March 2027.
How to compute an instalment
- Estimate total income for the full year under every head: salary, house property, business or profession, capital gains realised so far, interest and dividends.
- Subtract the deductions you are entitled to in the regime you will choose, and compute tax on the slabs with cess and any surcharge. Our slab guide has the table.
- Subtract tax that will be deducted or collected at source during the year, and any relief.
- If the balance is ₹10,000 or more, multiply by the cumulative percentage for the instalment and subtract what you have already paid.
Revise the estimate at each date. A consultant whose income jumps in October pays the catch-up in December; the law expects a reasonable estimate at each date, not foresight.
Capital gains and windfalls. A gain, a lottery win or a dividend cannot be predicted. Where such income arises after an instalment date, no interest is charged for the earlier shortfall provided the tax on it is paid in the remaining instalments, or by 31 March if it arises after 15 March.
How to pay
On the e-filing portal use e-Pay Tax, choose Income Tax, the assessment year following the financial year, and Advance Tax (code 100) as the type of payment. Pay by net banking, debit card, UPI or over the counter with the generated challan. The payment appears in Form 26AS and the Annual Information Statement within days, and is claimed in the return under taxes paid. Keep the challan: the BSR code, date and serial number are asked for when filing.
Interest when you fall short
Section 234C, for deferring instalments. Simple interest at 1 percent a month on the shortfall against each cumulative target: for three months on the June, September and December shortfalls, and for one month on the March shortfall. No interest is charged for June and September if at least 12 percent and 36 percent have been paid.
Section 234B, for underpaying overall. If advance tax paid by 31 March is less than 90 percent of the assessed tax, interest at 1 percent a month runs on the shortfall from 1 April of the assessment year until the tax is paid.
An example. A freelancer’s tax for the year after TDS is ₹2,00,000 and she pays nothing until she files in July. Interest under 234C: 1 percent for three months on ₹30,000, on ₹90,000 and on ₹1,50,000, and one month on ₹2,00,000, which is ₹10,100. Interest under 234B: 1 percent a month on ₹2,00,000 for April to July, ₹8,000. Total ₹18,100, or about 9 percent of the tax, for doing nothing.
For income earned from 1 April 2026 these provisions are section 424 (interest for default, formerly 234B) and section 425 (interest for deferment, formerly 234C) of the Income-tax Act, 2025, with the same rates; section 425 now states the three-month charge as 3 percent of each early shortfall. The liability itself is in section 404.
Salaried with other income: the simpler route
An employee can declare other income, and the tax deducted on it, to the employer in Form 122 or the payroll portal, and the employer will deduct the additional tax from salary across the remaining months. That replaces advance tax entirely and avoids interest, as long as the declaration is made early enough in the year.
Our tax planning service computes and calendars the instalments; businesses and freelancers get them alongside the return.
Frequently asked questions
What are the advance tax due dates?
15 June (15 percent), 15 September (45 percent cumulative), 15 December (75 percent) and 15 March (100 percent). Presumptive taxpayers pay the whole amount by 15 March.
Who is liable to pay advance tax?
Anyone whose tax for the year after TDS and TCS is ₹10,000 or more, except resident senior citizens without business or professional income.
What is the interest for not paying advance tax?
1 percent a month under section 234C on each instalment shortfall, and 1 percent a month under section 234B from April until payment where less than 90 percent was paid by 31 March.
Do salaried employees pay advance tax?
Only if TDS does not cover their total tax, for example because of rent, interest or capital gains. Declaring the other income to the employer avoids it.
How do I pay advance tax online?
Through e-Pay Tax on the income-tax portal: Income Tax, the relevant assessment year, payment type Advance Tax (100), then net banking, card or UPI.
What is the next advance tax due date?
The next date is 15 December 2026, when 75% of the tax for FY 2026-27, after TDS, should have been paid. The final instalment is due on 15 March 2027.
ITR Filing from ₹399, by a CA.
CA-prepared return with a regime comparison and e-verification, salaried from ₹399.
Professional fee shown; government charges at actuals, quoted in writing before you pay. GST at 18% extra.
See what is included and the full priceInstalments computed and calendared for you
Estimates revised each quarter, challans prepared, no 234B or 234C surprises in July.
Keep reading.
Interest under 234A, 234B and 234C: now sections 423, 424 and 425
Sections 423, 424 and 425 of the Income-tax Act, 2025 replace 234A, 234B and 234C: 1% a month for a late return and unpaid advance tax, 3% on instalment shortfalls.
Read guide→GuideTax on FD interest
Slab-rate tax, the TDS thresholds, Form 121 replacing 15G and 15H, cumulative FDs, and the senior citizen deduction.
Read guide→Free toolOld vs new tax regime calculator
Compare both regimes for FY 2026-27 and see which saves you more, before you file.
Open calculator→Official references
The statutory sources behind this page. We keep our guidance aligned to them: verify anything time-sensitive directly.
- Ministry of Corporate AffairsCompanies Act filings, forms and fee schedules
- Income Tax DepartmentReturns, forms, rates and e-filing utilities
- GST PortalRegistration, returns and rate notifications
Facts on this page are checked against these sources; the date of the last check is shown at the top of the page. It is general guidance, not advice on your specific facts. How we write and check our guides.