GST on rent: commercial, residential, and who pays
Rent is taxed at 18 percent or not at all, and the person who pays the tax to the government is sometimes the landlord and sometimes the tenant. Two changes, in July 2022 and October 2024, moved a lot of tenants into the second group without telling them.
Reviewed by Vijay Dhawan, Managing Partner, LexVerge LLP, on · Published
Quick answer
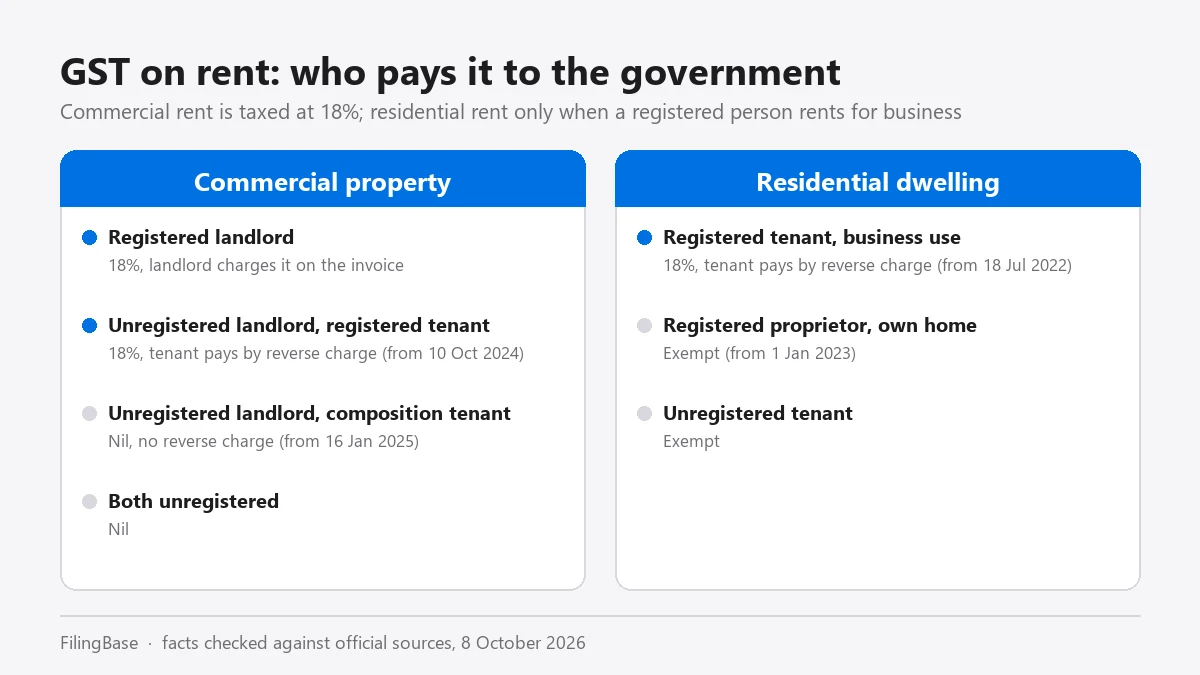
GST on rent is 18% on commercial property, and on residential dwellings rented by a GST-registered person for business. A registered landlord charges it on the invoice. Where the landlord is unregistered, a registered tenant pays it under reverse charge (commercial property from 10 October 2024, residential from 18 July 2022), except composition taxpayers for commercial rent from 16 January 2025. Residential rent paid by an unregistered person, or by a registered proprietor for their own home, is exempt. Input tax credit is available on commercial premises used for taxable business.
Need this done for you?
Renting out commercial property and crossing the threshold? Get your GSTIN without the back-and-forth.
₹299, no government fee
The matrix
| Property | Landlord | Tenant | GST | Who pays it to the government |
|---|---|---|---|---|
| Commercial | Registered | Anyone | 18% | Landlord, charged on the rent invoice |
| Commercial | Unregistered | Registered (regular scheme) | 18% | Tenant, under reverse charge, from 10 October 2024 |
| Commercial | Unregistered | Registered under composition | Nil | No reverse charge, from 16 January 2025 |
| Commercial | Unregistered | Unregistered | Nil | n/a |
| Residential dwelling | Anyone | Registered person, for business use | 18% | Tenant, under reverse charge, from 18 July 2022 |
| Residential dwelling | Anyone | Registered proprietor, in a personal capacity for own residence | Exempt | n/a |
| Residential dwelling | Anyone | Unregistered person | Exempt | n/a |
A landlord must register once aggregate turnover, including rent from all properties and any other business under the same PAN, crosses ₹20 lakh in a year (₹10 lakh in special category states). Rent from residential property let for residence counts towards the threshold even though it is exempt.
Want the books and the returns handled together? See our accounting and bookkeeping services.
Claiming input tax credit? GSTR-2B explained shows how the statement generated on the 14th decides what you can claim.
Commercial property
Rent for shops, offices, warehouses, godowns and land let for business is a taxable service at 18 percent. A registered landlord raises a tax invoice and the tenant, if registered, takes input tax credit against output tax.
Since 10 October 2024, where the landlord is not registered and the tenant is, the tenant pays the 18 percent under the reverse charge mechanism. This caught small landlords’ tenants by surprise: a registered business renting a shop from an individual with rent below the ₹20 lakh threshold now owes GST every month, in cash, because reverse charge liability cannot be paid from the credit ledger. The tenant issues a self-invoice within 30 days of the rent payment, reports the supply in GSTR-3B, pays the tax, and takes the credit in the same return if the premises are used for taxable business. Net cost nil, but only if it is done; if it is not, the demand comes with interest at 18 percent.
Residential property
Rent for a residential dwelling used as a residence is exempt. The exemption was narrowed from 18 July 2022: where the tenant is a GST-registered person, the rent is taxable at 18 percent and the tenant pays under reverse charge, whoever the landlord is. The common cases are a company renting flats for employees or a guest house.
From 1 January 2023 an exception protects registered proprietors: where an individual who happens to be GST-registered rents a home in a personal capacity for their own residence, and not on account of the business, the exemption continues.
Credit on residential rent paid under reverse charge is the contested part. Where the dwelling houses employees as a term of employment, the credit is generally taken; where it is for the personal benefit of a director or proprietor, it is blocked as personal consumption. Record the purpose in the lease and the board resolution.
Value, deposits, and TDS
GST is charged on the rent plus any charges the lease makes the tenant bear as part of the letting: maintenance collected by the landlord, property tax reimbursed, and furniture or fit-out hire. A refundable security deposit is not consideration; a deposit adjusted against rent is, at the time of adjustment. Electricity recovered at actuals through a separate meter, as a pure agent, stays outside the value.
Income-tax TDS is separate and computed on the rent excluding GST; see our TDS on rent guide.
What tenants should do this month
- List every property you rent and check each landlord’s GSTIN on the portal. A landlord who stopped charging GST may have cancelled registration.
- For unregistered landlords of commercial premises, and for residential premises used for business, start monthly self-invoices and pay reverse charge in GSTR-3B.
- For periods since October 2024 that were missed, pay with interest through DRC-03 before a notice arrives; the credit is still available within the usual time limit.
- Put the GST position in the lease: who bears it, and the landlord’s duty to tell you if their registration status changes.
Our return filing service tracks reverse charge items as part of the monthly cycle, and notice replies cover the demands already issued.
Frequently asked questions
Is GST applicable on rent?
Yes, at 18 percent on commercial property, and on residential dwellings rented by a GST-registered person for business. Residential rent paid by an unregistered person, or by a registered proprietor for their own home, is exempt.
Who pays GST on rent when the landlord is unregistered?
A registered tenant pays it under reverse charge: for commercial property since 10 October 2024 and for residential dwellings since 18 July 2022. Composition taxpayers are excluded for commercial rent from 16 January 2025.
Can I claim input tax credit on GST paid on rent?
Yes for commercial premises used for taxable business, including tax paid under reverse charge. For residential premises it depends on the use, and credit for personal residence is blocked.
When must a landlord register for GST?
When aggregate turnover under the PAN, including all rent and any other business, exceeds ₹20 lakh in a year, or ₹10 lakh in special category states.
Is GST charged on the security deposit?
Not on a refundable deposit. If the deposit is adjusted against rent or forfeited, GST applies at that point.
GST Return Filing from ₹149 a month, by a CA.
GSTR-1 and GSTR-3B every cycle, reconciled against GSTR-2B before filing.
Professional fee shown; government charges at actuals, quoted in writing before you pay. GST at 18% extra.
See what is included and the full priceReverse charge on rent, handled monthly
Self-invoices, GSTR-3B reporting and credit taken in the same return. From ₹499 a month.
Keep reading.
Reverse charge mechanism in GST: when the buyer pays the tax
When GST is payable by the recipient: the notified services, rent from unregistered landlords, paying RCM in cash, claiming ITC, and the 30-day self-invoice.
Read guide→GuideIncome from house property
Annual value, the 30% deduction, interest limits by regime, self-occupied vs let-out, and set-off of losses.
Read guide→GuideInput Tax Credit Under GST: The Four Conditions, GSTR-2B and IMS, the Time Limit, the 180-Day Rule and the Blocked Credits
The four conditions for credit, why GSTR-2B and the invoice management system now decide it, the 30 November deadline, the 180-day rule and the blocked list.
Read guide→Official references
The statutory sources behind this page. We keep our guidance aligned to them: verify anything time-sensitive directly.
- Ministry of Corporate AffairsCompanies Act filings, forms and fee schedules
- Income Tax DepartmentReturns, forms, rates and e-filing utilities
- GST PortalRegistration, returns and rate notifications
Facts on this page are checked against these sources; the date of the last check is shown at the top of the page. It is general guidance, not advice on your specific facts. How we write and check our guides.